USA
 Canada
 Australia

Introduction
Tax season pressure rarely comes from a single deadline. It builds when client files arrive at the same time, bookkeeping is incomplete, review queues start growing, and available staff are already managing competing priorities. For Canadian accounting firms, effective tax season workflow planning for accounting firms means forecasting workload before the rush, identifying capacity gaps early, and creating a workflow that can handle both expected and unexpected work. For firms looking to strengthen their bookkeeping and accounting capacity, NCSGX provides support that can help keep financial work organized and moving throughout the season. With the right plan in place, firms can enter the 2026–27 tax season with clearer priorities, better workload visibility, and greater control over their capacity.
Key Takeaways
- Start accounting firm capacity planning for tax season early by forecasting client volume, preparation hours, review time, and staff availability.
- Build a tax deadline calendar planning Canada process around major individual, corporate, GST/HST, and payroll-related deadlines.
- Identify accounting firm workflow bottlenecks tax season before they create review queues, rework, or delayed filings.
- Establish a practical seasonal tax preparer hiring timeline that allows enough time for recruitment, onboarding, training, and system access.
- To avoid tax season overwhelm accounting firm, set earlier client document deadlines and protect senior review capacity.
- Use workload forecasting, delegation, and capacity buffers to reduce tax season burnout accounting staff and keep work moving during peak periods.
Accounting Firm Capacity Planning for the 2026–27 Tax Season
The 2026–27 tax season will bring a familiar mix of individual returns, corporate filings, bookkeeping work, GST/HST obligations, client queries, and review requirements. Effective accounting firm capacity planning tax season means looking beyond the number of clients and estimating the actual time, skills, and review capacity each file requires. By forecasting workload early, planning staffing, setting internal deadlines, and identifying potential bottlenecks, Canadian accounting firms can keep work moving while reducing last-minute pressure. A structured approach also makes it easier to decide when to use seasonal staff, cross-trained employees, or outsourced support to handle periods of higher demand.
Why Tax Season Workflow Planning Matters for 2026–27
A firm can have enough employees on paper and still run short of capacity. A senior may become the review bottleneck, bookkeeping may remain unfinished, or client documents may arrive too late for the planned preparation window.That is why tax season workflow planning for accounting firms should look beyond headcount. Review hours, staff availability, client complexity, recurring bookkeeping, and internal deadlines all need to be considered together.
Start by reviewing the previous season. Identify periods when work accumulated, files waited for review, or senior staff had to step into routine production. These are useful indicators when building an accounting firm capacity planning tax season model.
Mapping the 2026–27 Tax Deadline Calendar Before You Plan
Before you allocate people or workload, build a tax deadline calendar planning Canada that reflects the filings affecting your firm most. For the 2026 tax year, key dates include:
- Individual T1 returns: April 30, 2026 for most taxpayers; self-employed individuals and their spouses have until June 15, 2026 to file, though any balance owing is still due April 30.
- T4 slips: Due to the CRA and employees by the last day of February. For 2026 slips, the deadline is March 1, 2027, since February 28, 2027 falls on a Sunday.
- Corporate T2 returns: Generally due six months after fiscal year-end. A December 31, 2025 year-end means a June 30, 2026 filing deadline, with tax balances typically due two months after year-end (or three months for eligible CCPCs).
- GST/HST returns: Monthly and quarterly filers must file and pay one month after each reporting period ends. Annual filers generally have three months after fiscal year-end, with sole proprietors on a December 31 year-end filing by June 15 but paying by April 30.
These deadlines create overlapping workload peaks. Mapping them early helps you see when bookkeeping, payroll, and tax preparation will collide. Firms should verify filing and payment dates against the latest CRA tax deadlines for Canadian businesses and self-employed individuals and CRA personal income tax due dates when building their internal tax calendar.
Forecasting Client Volume Before the Rush Hits
Accounting firm capacity planning tax season becomes easier when client volume is converted into estimated hours.
Start with last year’s client list and divide it into practical categories:
- Routine individual returns
- Self-employed returns
- Corporate returns
- Clients requiring bookkeeping clean up
- New clients with uncertain preparation requirements
Then estimate preparation and review hours for each category. Add recurring bookkeeping requirements and identify clients who historically submit documents late.
For example, if 120 routine files require an average of 2.5 preparation hours, that represents 300 preparation hours before review. If 20 complex files require eight hours each, another 160 hours is required. Add review time, cleanup, meetings, and a reasonable buffer before deciding whether existing capacity is sufficient.
Staffing Models That Fit Canadian Accounting Firms
Not every capacity gap requires another permanent employee. The right model depends on whether the workload is recurring, seasonal, specialised, or temporary.
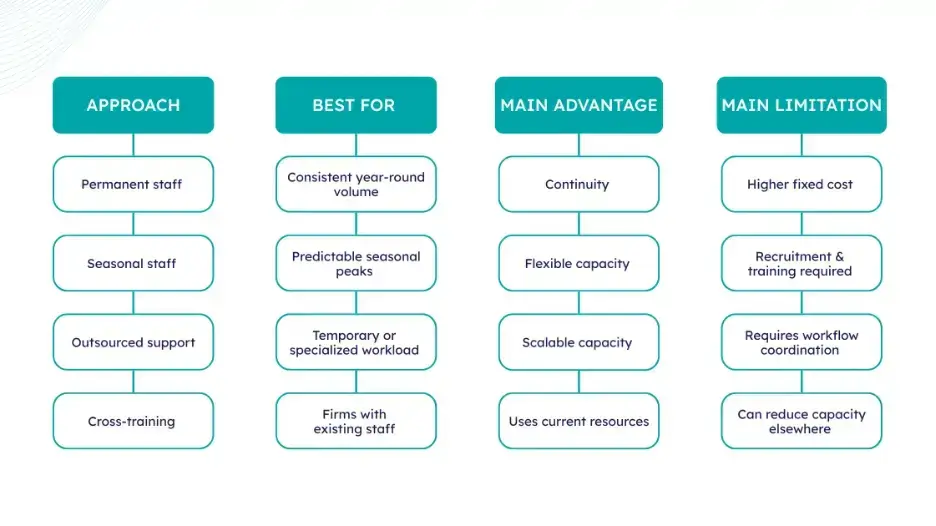
Setting a Seasonal Hiring Timeline That Actually Works
A seasonal tax preparer hiring timeline should be based on forecasted hours rather than a general sense that tax season is approaching. Define the skills required, recruitment lead time, onboarding needs, system access, expected start date, and review structure.
A practical seasonal tax preparer hiring timeline should also include an expected end date and clear handoff responsibilities. If training takes several weeks, hiring immediately before peak volume may provide too little capacity when it is needed most.
Fixing Workflow Bottlenecks Before They Cost You Time
Capacity issues are not always caused by a lack of staff. Accounting firm workflow bottlenecks tax season often arise from missing documents, incomplete bookkeeping, delayed reconciliations, manual data entry, or growing review queues. Mapping the workflow from client documents → bookkeeping → reconciliation → tax preparation → review → finalisation helps firms identify where work is slowing down.
For firms that need additional production capacity, outsourced bookkeeping can also help move routine reconciliation and bookkeeping work away from senior tax staff.
Avoiding Tax Season Burnout on Your Team
Tax season burnout accounting staff can be made worse by uneven workload allocation, repeated overtime, constant interruptions, and limited review capacity. A capacity plan should therefore protect people as well as deadlines.
To avoid tax season overwhelm accounting firm, should consider:
- Forecasting workload before peak volume
- Prioritising files by deadline and complexity
- Assigning clear file ownership
- Delegating routine production work
- Using temporary or outsourced support where appropriate
Tax season burnout accounting staff is not solved by simply asking people to work faster. Better allocation and earlier intervention are more practical approaches.
Setting Client-Facing Deadlines Without Losing Trust
Official CRA deadlines should not become your firm’s internal deadlines. Clients need earlier document collection dates so there is enough time for preparation, review, questions, corrections, approval, and filing. These internal dates should be built backward from the applicable CRA filing deadline, which can vary by taxpayer type, filing period, and return.
For example, a firm could set:
- Client documents due: 3–4 weeks before the filing target
- Preparation complete: 2 weeks before the filing target
- Review complete: 1 week before the filing target
- Client approval: several business days before filing
Communicate these dates through early-season reminders and engagement communications. Clear expectations reduce last-minute chasing and make tax deadline calendar planning Canada more manageable.
Building in a Buffer for the Unexpected
No capacity plan should assume 100% utilisation. Late documents, complex tax issues, rework, staff absence, CRA correspondence, bookkeeping clean up, and urgent client requests can all consume hours that were not in the original forecast.
A useful buffer does not mean leaving people idle. It means avoiding a plan where every available hour is already committed.
For example, if the forecast shows 900 hours of work and the team can realistically produce 950 hours, those 50 hours should not automatically be filled with additional work. That space gives the firm room to absorb exceptions without immediately creating accounting firm workflow bottlenecks tax season.
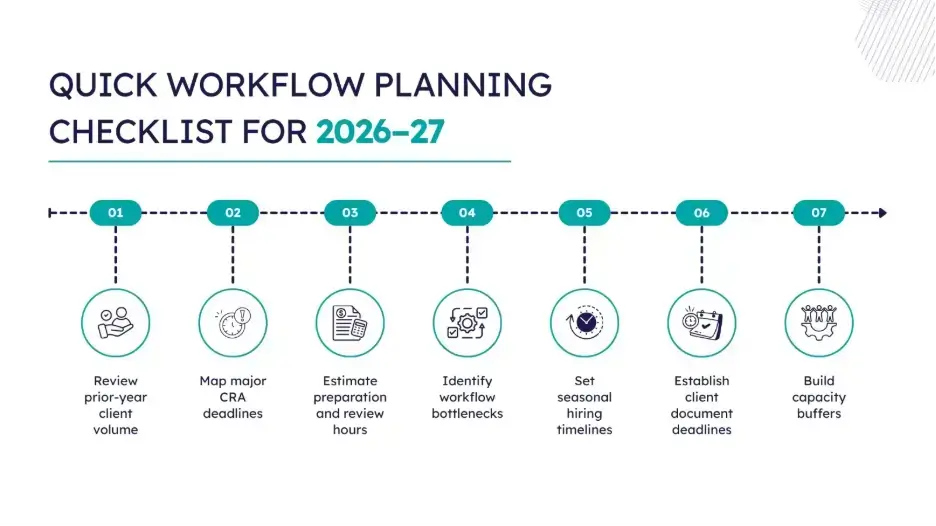
A strong plan should be reviewed again as client intake develops. Capacity planning is not a one-time spreadsheet. It is a working management process that should change when volume, staffing, or deadlines change.
Conclusion
A well-planned tax season helps accounting firms balance client demand, staff capacity, deadlines, and review workloads without relying on last-minute fixes. By addressing bottlenecks early and planning additional production support where needed, firms can enter the 2026–27 tax season with greater control and consistency. If your firm needs support with bookkeeping or accounting capacity, contact us to explore how NCSGX can help.
How NCSGX Can Help
When tax-season workloads increase, additional production capacity can help accounting firms keep bookkeeping, reconciliations, and other routine work moving while internal teams focus on preparation and review. NCSGX supports Canadian accounting firms with bookkeeping and accounting services that can help manage workload pressure and reduce workflow bottlenecks during busy periods.
Frequently Asked Questions (FAQ)
1. When should an accounting firm start tax season workflow planning?
Start several months before peak season. Review previous workloads, forecast upcoming files, and identify staffing or workflow gaps early.
2. How do you forecast staffing needs for tax season?
Estimate preparation, bookkeeping, review, and client-service hours based on file volume and complexity. Compare the workload with available staff capacity and include a reasonable buffer.
3. What's the difference between capacity planning and hiring seasonal staff?
Capacity planning assesses the firm’s overall workload and available resources. Seasonal hiring is just one option for addressing a capacity gap, alongside outsourcing, cross-training, or workload redistribution.
4. How can a firm avoid tax season burnout?
Plan workloads early, distribute files appropriately, protect senior review capacity, and set clear client deadlines. Additional temporary or outsourced support can help during peak periods.
5. What are the key 2026–27 CRA deadlines a firm should plan around?
Key deadlines include individual returns, T2 corporate returns, T4 filings, and GST/HST returns. Exact dates vary by taxpayer and filing period, so firms should verify the latest CRA guidance.
6. How far in advance should seasonal tax preparers be hired?
Hire early enough to allow for recruitment, onboarding, training, and system access before peak workload begins. The timing should be based on the firm’s forecasted workload and staffing gap.