USA
 Canada
 Australia

Introduction
A busy month-end can leave a CPA firm balancing reconciliations, client documents and bookkeeping deadlines alongside tax or year-end work. Bookkeeping outsourcing for CPA firms can move some of this recurring production work to an external team while the firm keeps control of the client relationship. NCSGX Canada supports this type of accounting workflow for Canadian firms.
So, what does outsourcing look like in practice? The external team may handle defined bookkeeping tasks, while the CPA firm remains responsible for review, client communication, and the overall workflow. The exact arrangement depends on the firm’s processes, engagement, and client needs.
Key Takeaways
- Outsourcing usually covers defined bookkeeping production work, not the entire client relationship.
- Monthly work can include transaction entry, reconciliations, payables, receivables, and GST/HST-related bookkeeping.
- Review points should be established before work moves to the next stage.
- CRA account access is separate from ordinary bookkeeping access.
- The outcome depends on clear processes, communication, and internal ownership.
What Bookkeeping Outsourcing Actually Looks Like for a CPA Firm
A Canadian CPA firm can reach a point where bookkeeping work is steady, but internal capacity is not. Several client files may need month-end work while senior staff prepare for tax or year-end deadlines. The issue is often recurring production work.
That is where bookkeeping outsourcing for CPA firms comes into the picture. But what does it look like once the work leaves the internal team? In practice, the model is usually more controlled than handing a client file to an outside provider. The scope is defined, work follows an agreed workflow, and the firm keeps oversight of the client relationship and review process.
What Bookkeeping Outsourcing Means for a CPA Firm
For a CPA firm, outsourcing usually means moving specific recurring bookkeeping tasks to an external team. The firm may keep client communication, review, adjustments and higher-level accounting work in-house. The split depends on the engagement and workflow.
The outsourced scope might include transaction entry, bank and credit-card reconciliation, accounts payable, accounts receivable, month-end bookkeeping, business records, GST/HST-related support, cleanup work and year-end bookkeeping.
The external team works within boundaries set by the firm, such as client instructions, deadlines and review procedures. This is also the practical role of outsourced bookkeeping for accountants: move suitable production work elsewhere while the firm retains the client relationship and review structure. Firms looking at a broader support model can also explore accounting support for firms as part of their outsourcing approach.
How the Outsourced Bookkeeping Workflow Works Day to Day
There is no single workflow for every firm. A typical monthly cycle may look like this:
- Client documents and transactions become available.
- The external bookkeeping team reviews the assigned work and checks for missing information.
- Transactions are categorized and entered according to the firm’s instructions.
- Bank and credit-card accounts are reconciled.
- Questions, unusual transactions and missing documents are flagged.
- The agreed bookkeeping work is completed.
- A CPA or designated reviewer checks the file.
- Review notes are addressed and corrections are made.
- The file moves to the next stage, such as client reporting, GST/HST work, tax preparation or year-end adjustments.
So, how does outsourced bookkeeping work in a real firm? The handoff needs to be clear. The external team should know what it owns, when to escalate and when the file must be ready.
That is why outsourcing for accounting firms must connect with the firm’s existing review process. Firms looking at the underlying bookkeeping process can also review NCSGX’s bookkeeping services for an overview of the tasks and workflow involved.
Where Outsourced Bookkeeping Fits into Compilation, Tax and Year-End Work
Bookkeeping often sits at the beginning of compilation work, tax preparation, GST/HST reporting and year-end close. An external team can prepare recurring records so the firm’s internal team can focus on review and adjustments. Missing documents can also be identified earlier.
Offshore bookkeeping for accountants can fit this model as well. Location does not remove the need for clear scope, review and controls. A firm considering an offshore arrangement should also consider how client information is transferred, stored and accessed.
Professional Responsibilities That Stay with the CPA Firm
Outsourcing changes where tasks are performed. It does not automatically remove the firm’s responsibility for client information, access and review. Before sharing information, the firm should understand its confidentiality and privacy obligations and establish appropriate controls.
The CPA firm should know where client records are held and how they can be retrieved. CRA recordkeeping requirements should form part of the overall process.
CRA account access is a separate issue. A person or business can authorize a representative to deal with the CRA, but an outsourced bookkeeper does not automatically receive that authority because they work on bookkeeping tasks. Access should be considered deliberately and provided only where appropriate for the assigned work.
For offshore bookkeeping for accountants, the firm should also consider how personal information is transferred, stored and accessed.
Common Challenges CPA Firms Face When Outsourcing Bookkeeping
Most outsourcing problems are workflow problems. Poorly documented processes, incomplete client records and unclear instructions can slow a file down. Review capacity matters too. If nobody inside the firm has time to review completed work, adding an external production team does not solve the bottleneck.
Access is another consideration. Permissions should match the work being performed, with a clear escalation process for unusual items. With white label bookkeeping, client communication, review notes and corrections should still have an identified owner.
For outsourcing for accounting firms, price is only one consideration. Process, controls and review structure also affect the arrangement.
What a CPA Firm Should Have in Place Before Outsourcing
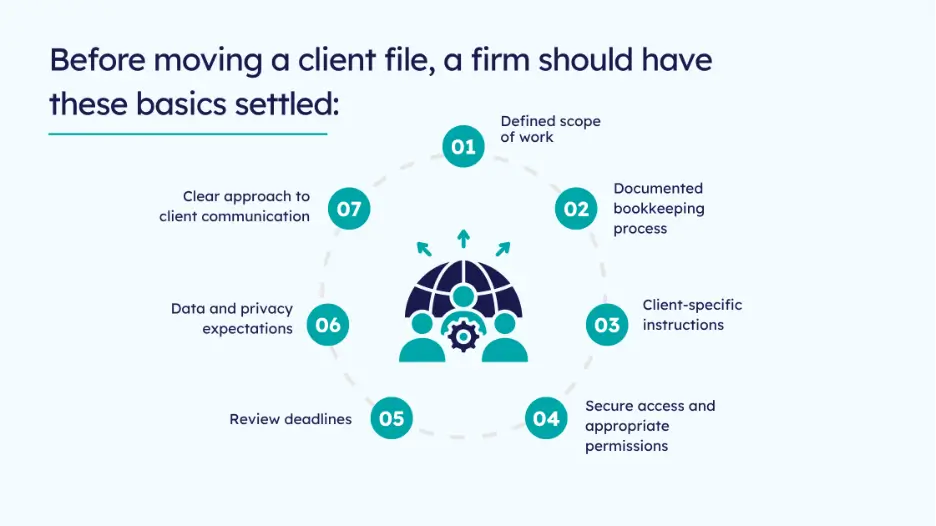
For white label bookkeeping, the external team needs enough information to work consistently while the CPA firm retains review control. For offshore bookkeeping for accountants, the firm should also understand where information is processed and how access is managed.
Conclusion
Bookkeeping outsourcing for CPA firms is ultimately a workflow decision, not simply a staffing decision. The firm needs to define the scope, document the process and establish review points before work moves outside the internal team.
Privacy and record handling need attention too. System access should match the work. CRA access should be treated separately from ordinary bookkeeping access, while the CPA firm remains clear about client ownership and review.
If you are considering whether this approach fits your practice, you can contact us to discuss the workflow and capacity requirements.
How NCSGX Canada Can Help
NCSGX Canada can support CPA firms that want to move defined bookkeeping production work into an external workflow without changing how the firm manages its client relationships. The arrangement can be built around agreed tasks, documented processes, review points and flexible capacity, with the CPA firm retaining oversight of the final work.
Frequently Asked Questions (FAQ)
1. Do Canadian CPA firms need client consent to outsource bookkeeping?
Not always. The answer depends on the engagement terms, confidentiality obligations, privacy requirements and how the outsourcing arrangement is structured. Firms should review these points before sharing client information with an external provider.
2. Can outsourced bookkeepers work directly in a client's QuickBooks Online or Xero file?
Yes, they may be able to work directly in the client’s cloud accounting file when appropriate access is provided. The CPA firm should control permissions, define the scope of work and maintain its review process.
3. Who is responsible if an outsourced bookkeeper makes an error on a GST/HST return?
It depends on the firm’s engagement and review process. The firm should clearly define who prepares the records, who reviews them and who handles corrections before a GST/HST return is completed.
4. Can a CPA firm outsource bookkeeping for clients based in Quebec?
Yes, outsourcing may be possible, but Quebec privacy requirements should be considered. Firms should understand how client information will be handled and review the requirements that apply to their specific arrangement under Law 25.
5. Should outsourced bookkeeping staff have access to a client's CRA My Business Account?
Not automatically. Bookkeeping access and CRA representative access are separate matters. If CRA access is needed, the firm should use the appropriate authorization process and provide only the access required for the work.
6. Does a CPA firm need to tell clients it uses a white-label bookkeeping provider?
There is no single answer for every arrangement. The firm should consider its engagement terms, client expectations, confidentiality and privacy requirements before using a white label bookkeeping provider.